The Analysis of Financial Markets
In physics, the other social sciences,
economics, and portfolio management a lot remains unknown, part of which is not
subject to rational inquiry. In physics, for instance NASA writes,“
Some 13.8 billion years ago, the universe began with a rapid expansion we call
the big bang. After this initial expansion which lasted a fraction of a second,
gravity started to slow the universe down. But….Nine
billion years after the universe began, its expansion started to speed up,
driven by an unknown force that scientists have named dark energy. But what
exactly is dark energy? The short answer is: We don’t know. But we do know that
exists, its making the universe expand at an accelerating rate, and
approximately 68.3 to 70% of the universe is dark energy.”
The current buzz-word, which
is absolutely true, comes from A.I. It is context.
Context determines the applicability of logic, whether in physics, politics,
economics, or portfolio management. The rules of logic we inherited from the
Greeks, and each field now has its objects to which logic applies. In physics,
for example, there is the logic of interacting elementary particles. In
political science, there is the logic of political theory and its application
to the politics of actual societies. In economics, there is the logic of self-interest
applied to market behavior. In portfolio management, there is the logic of
self-interest applied to portfolio risk and return.
As the below indicates, some of the best minds have
tried to divine the stock market, thus the origins of mathematical economics
which enabled the quantification of portfolio risk and return. We shall follow
with an alternative.
In his 1900 PhD random walk thesis studying price
fluctuations on the Paris Bourse, the candidate, Louis Bachelier, sat before
the great French mathematician Henri Poincaré. “While he celebrated use of the
(Gaussian) bell curve in the physical sciences, Poincaré
thought caution needed to be exercised in applying it to human behavior….’One
might fear that the author has exaggerated the applicability of Probability
Theory as has often been done….Fortunately, this is
not the case. 1’”
What Bachelier had properly assumed was that any excursions from
this price had to be small.
Fast forward to a paper by Milton Friedman,“Essays in Positive Economics (1953)”
however, seemed to justify disregarding the assumptions in favor of the
results. The ultimate differences, however, are the differences between
deduction and induction. In an example from real life, Friedman asks the reader
to imagine:
“…an expert billiard player. It seems not at all
unreasonable that excellent predictions would be yielded by the hypothesis that
the billiard player made his shots as if he knew the complicated mathematical
formulas that would give the optimum directions of travel, could estimate
accurately by eye the angles, etc., describing the location of the balls, could
make lighting calculations from the formulas, and could then make the balls
travel in the direction indicated by the formulas. Our confidence in this
hypothesis is not based on the belief that billiard players, even expert ones,
can or do go through the process described; it derives rather from the belief
that, unless in some way or the other they were capable of reaching essentially
the same result, they would not in fact be expert billiard players.
It is only a short step from these examples to the
economic hypothesis that under a wide range of circumstances individual firms
behave as if they were seeking rationally to maximize their expected
returns…and had full knowledge to succeed in this attempt, as if, that
is, they knew the relevant costs and demand functions, calculated marginal cost
and marginal revenue from all the actions open to them, and pushed each line of
action to the point at which the relevant marginal cost and marginal revenue
were equal (if they had no competitors with a different cost structure)….The
billiard player, if asked how he decides where to hit the ball, may say that he
‘just figures it out’ but then also rubs a rabbit’s foot just to make sure; and
the businessman may well say that he prices at average cost…unless the behavior
of businessmen in some way or other approximated behavior with the maximization
of returns, it seems unlikely that they would remain in business for long.”
Practical activity is bottom-up. It has
to consider context and must therefore be inductive, with
generalizations necessarily general. In contrast, theoretical activity like
math, comes from the opposite top-down direction. Its conclusions are certain,
but brittle when they encounter the real world.
A 1965 landmark paper by the economist Paul Samuelson
proved, “Properly Anticipated Prices Fluctuate Randomly.” He started the whole field of quantitative
economics by stating the market postulate that prices were a simple Martingale 2,
slightly simplifying, E[Xn+1] = Xn for all n. In other words, at
any particular instance, the market is always fairly priced because it reflects any new information that
has occurred. As a result of this paper, the language of economics became
mathematical.
A Martingale process is general; it does not require
the data to follow a normal Gaussian distribution. But assuming the latter,
Harry Markowitz then applied the Central Limit Theorem of statistics to
portfolio management to derive exact portfolio risk and return. In statistics,
aggregated random variables approach a Gaussian distribution only if their
underlying variance is finite. But real-world financial returns regularly display
fat-tailed (non-Gaussian) distributions with extreme price movements,
invalidating models that rely on exact normal distribution trade-offs between
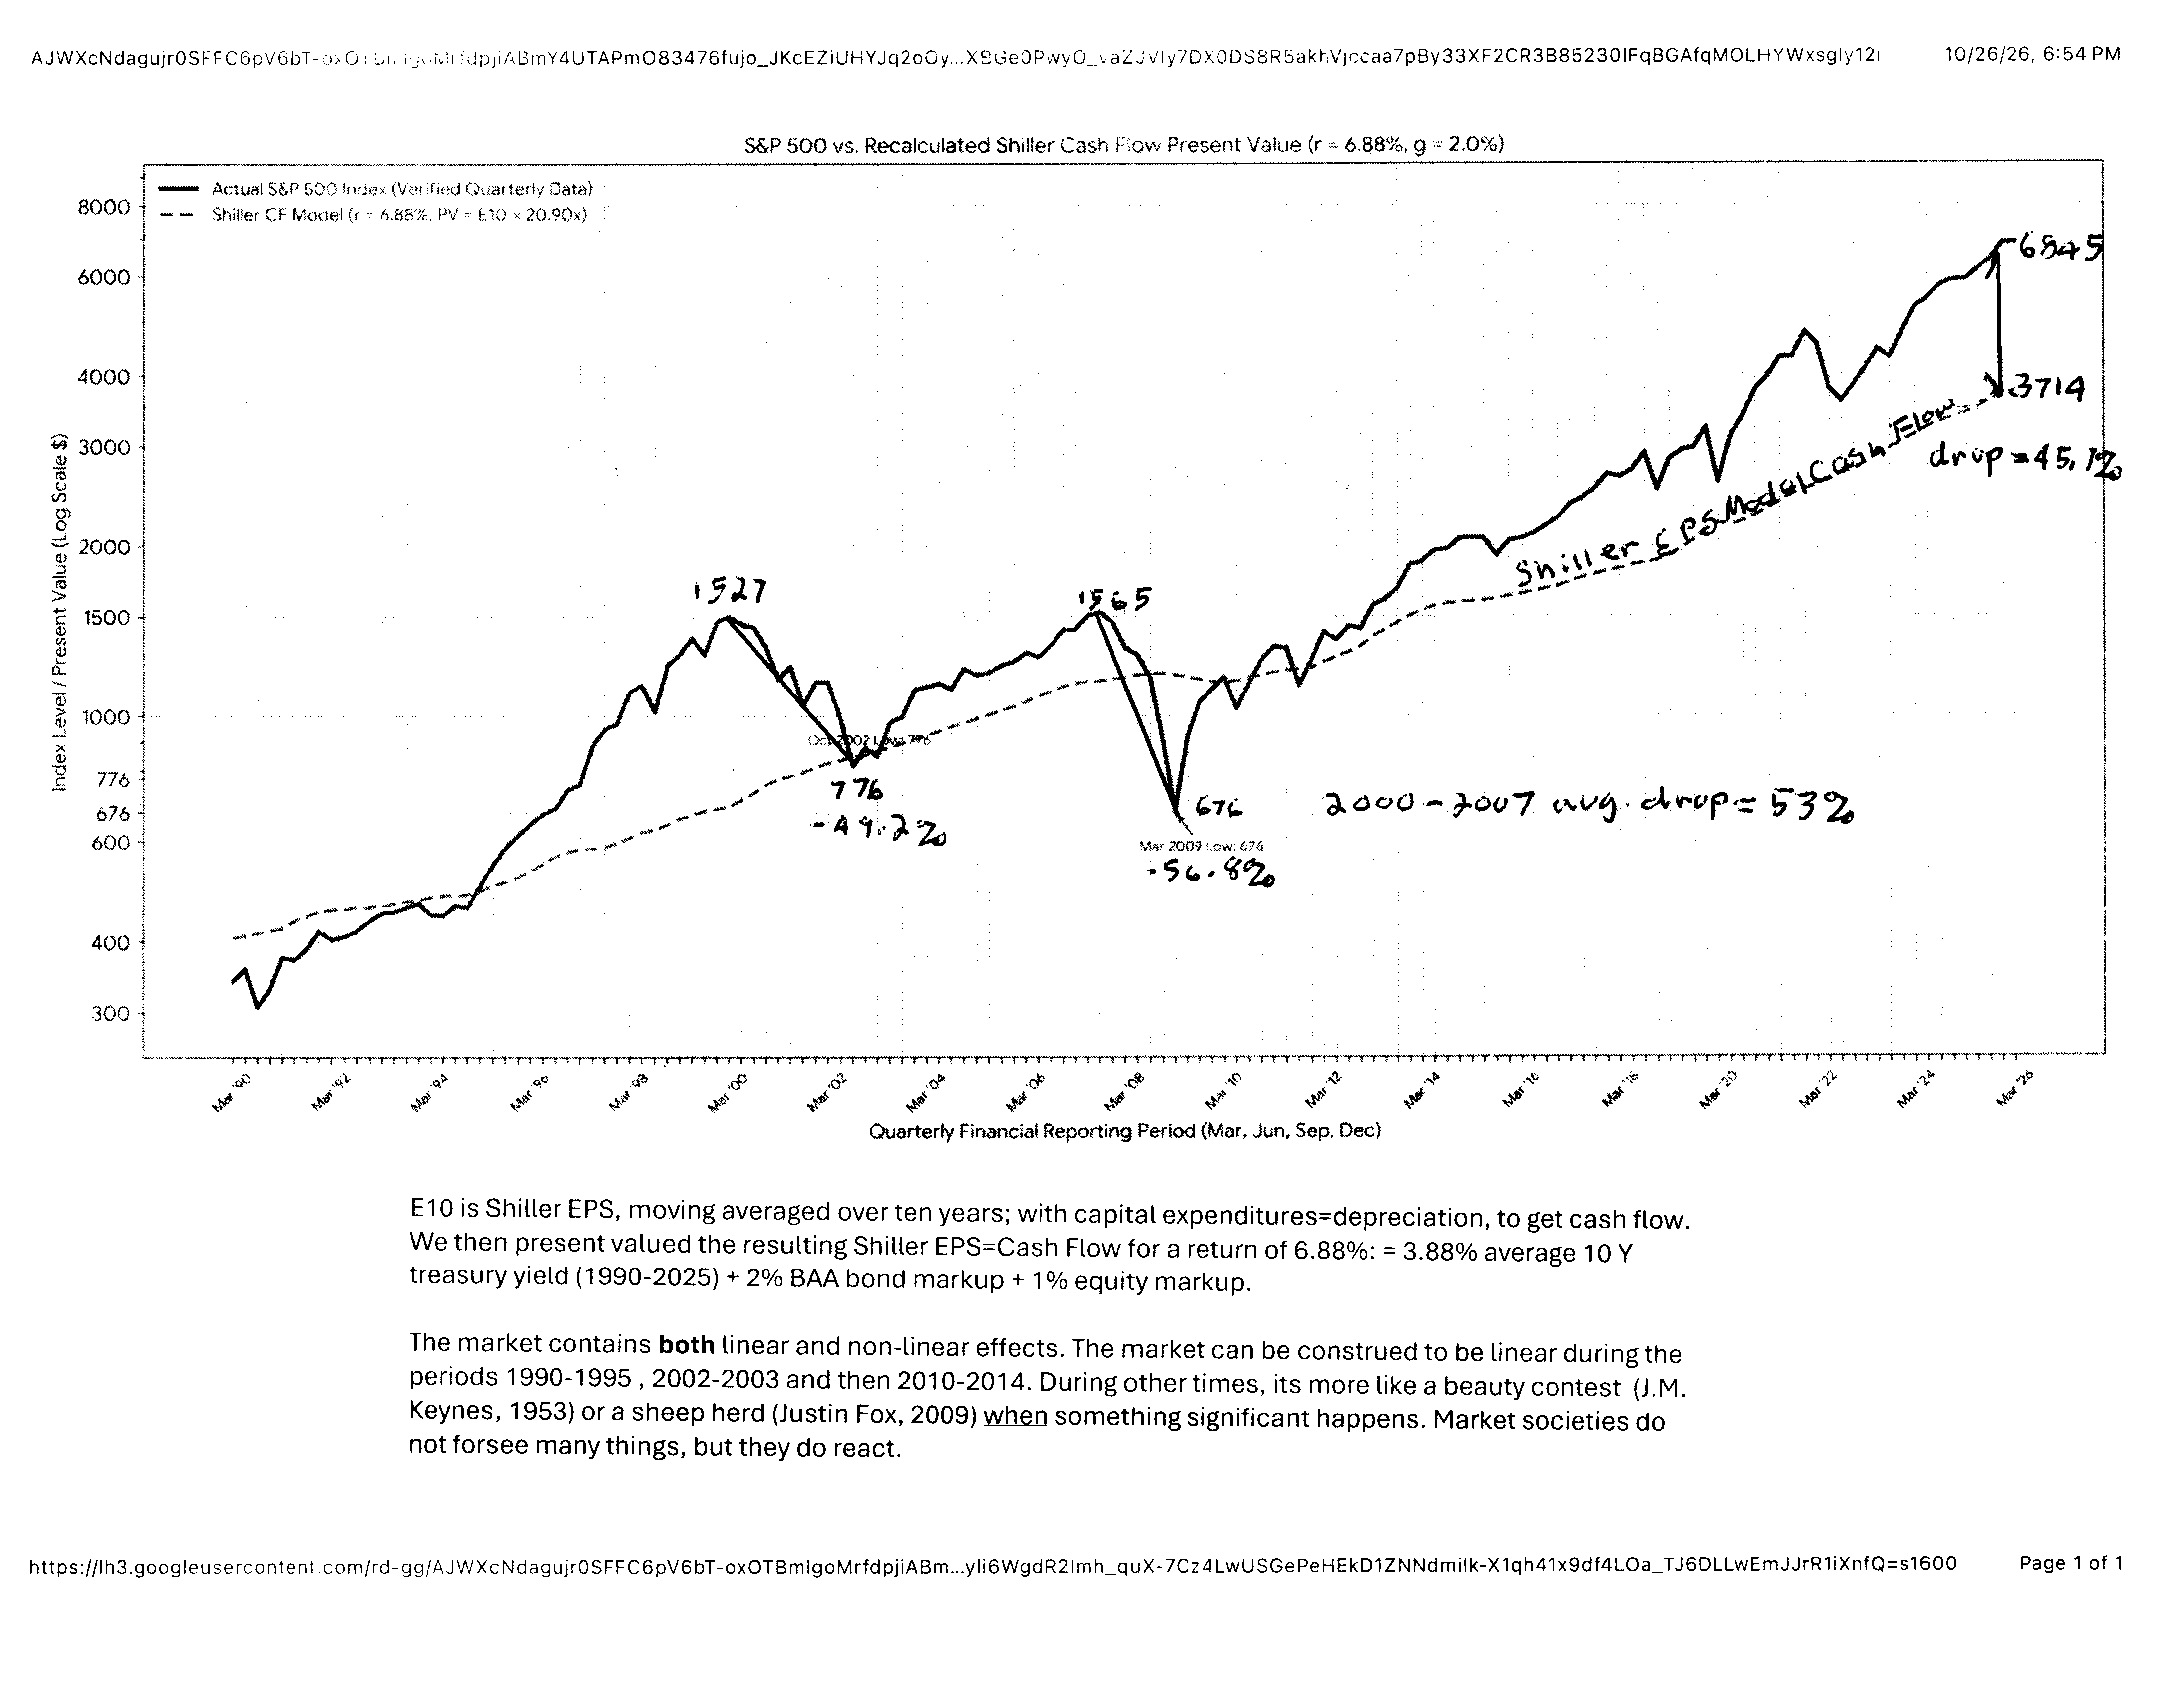
risk and return. A clear example of this can be seen on this graph of the S&P 500
between 1960 and 2026. In 2022, one cyclical economic bubble downturn merged
with the A.I. bubble upturn, creating a single bubble with a very large
variance.
We once thought that it would suffice to publish a present
value formula for establishing rates of return and therefore valuing the
S&P 500. Due to bubbles and their aftermath, the real stock market can be
very far from present value for a long time. Here is what we think: After
valuing the long-term obvious, for instance all venture capital deals require
the projection of immense profits, the markets are ultimately reflective of
what happens currently in the real economy. They will be very short-term, but according
to the liberal tradition that the markets and marketplaces should ultimately
reflect the societal truth.
It makes no sense to try to compete with Wall Street
in the short-term. We therefore take a medium-term approach. The S&P 500
and individual companies are, in essence, projects with cash flows and rates of
return. This viewpoint allows us to place uncertainty where it belongs in a
business sense on properly priced projects, rather than on the efficacy of generalized
portfolio models. Will Nike be able to replace or recapture the Chinese market
(we think the risk that it can do so is high); will Verizon be able to effect a turnaround (we obvious think that it can); and so
on.
We also apply risk control to our “projects.” Our
portfolio contains almost exclusively interest sensitive bonds, stocks and
non-interest sensitive money market funds. Thus it possible to calculate a very
approximate duration for the entire portfolio.
1 Justin Fox; “The Myth
of the Rational Market”; Harper Business; New York, N.Y.; 2009; p.p. 7-8.
2 The original
French “Martingale” was a betting strategy that appeared in the 18th
century.
__
This website has created the basis for present valuing
the S&P 500. For valuing individual companies, we strongly suggest the
lapidary (first edition) “Value Investing” by Bruce Greenwald (2001), which
also contains a corporate present value table on page 144.